Opening Range Duration Selection
Ten minutes of data provides a narrow window into the immediate volatility of an asset. The observations recorded at orb trading opening bell dianaliang focus on the mechanics of how market open volatility dictates the selection of a specific timeframe. Selecting the wrong interval for an orb strategy leads to false signals or missed moves during regular trading hours. An intraday trader must match the duration of the candle to the speed of the price action to maintain an edge.
The Five Minute Range
A five minute range works best for assets with high relative volume and tight spreads. High volatility stocks often clear their initial boundaries quickly. A 5 minute setup captures the immediate reaction to the cash open. This timeframe requires rapid execution because the opening range breakout happens fast. If the price moves too quickly, the signal becomes invalid before an order can be filled. High speed assets move through these levels with minimal hesitation, making the five minute range a tool for catching the initial momentum burst.
The Fifteen Minute Range
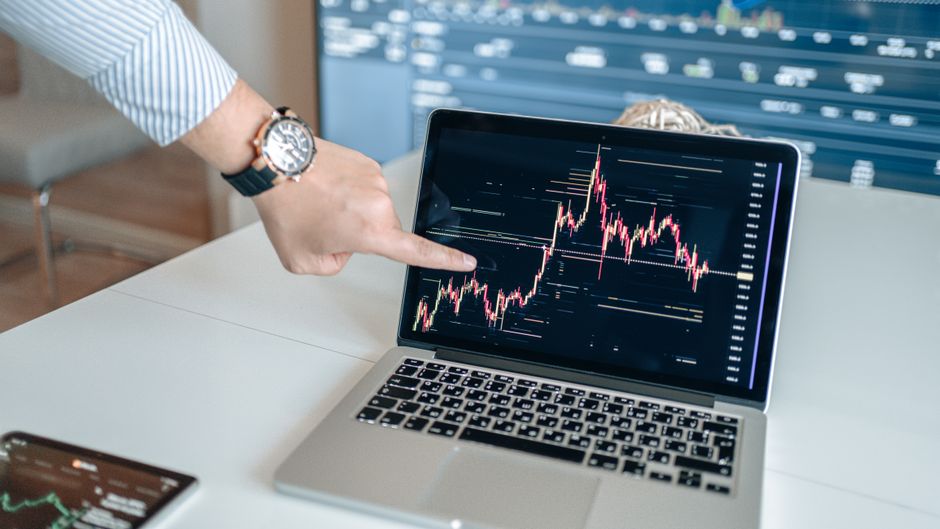
Standard volatility often suits a fifteen minute range. Many liquid equities establish a clear direction after the first fifteen minutes of the session. This duration filters out the noise found in the first few candles. A 15 minute setup provides a more stable structure for identifying the session high or low. Using this timeframe reduces the frequency of whipsaws. The price action tends to consolidate briefly before a sustained move develops. This middle ground is a common choice for assets that do not exhibit extreme parabolic moves immediately after the bell.
The Thirty Minute Range
Lower volatility or heavy institutional accumulation often requires a thirty minute range. A 30 minute window allows the initial chaos of the opening bell to settle. This period captures a broader view of the supply and demand balance. When an asset moves slowly, a smaller timeframe produces too many false breakouts. The thirty minute range provides a structural anchor for the rest of the morning. It identifies the true direction of the trend after the premarket orders are fully absorbed by the limit orders on the books.
Matching Duration to Volatility
Volatility dictates the math of the breakout. High ATR assets require longer durations to prevent premature entries. Low ATR assets require shorter windows to capture any meaningful movement. A mismatch between the asset speed and the selected timeframe leads to poor execution. If the range is too short, the breakout is just noise. If the range is too long, the move is already halfway finished by the time the signal triggers. Success depends on the mechanical alignment of the timeframe to the realized volatility of the asset during the first hour.